Avoid costs with business liability insurance
- Edited 11 September 2026
- 2 min
- Starting
- KVK Editors
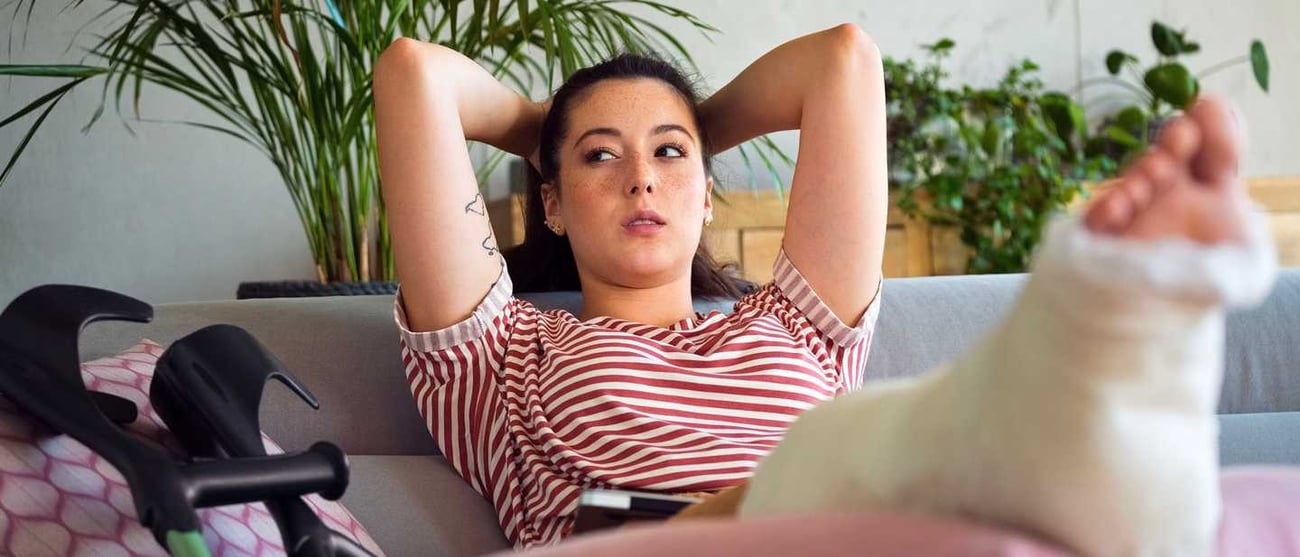
Suppose a client trips over a loose cord in your office. This causes them to break a leg and they are temporarily unable to work. As a business owner, you have to pay for the damage you cause while working. Read here how to avoid financial problems with business liability insurance.
What do you need to arrange when starting a business?
Answer the questions on Business.gov.nl and see the steps that are important in your situation.
What is business liability insurance?
Business liability , known as bedrijfsaansprakelijkheidsverzekering (AVB) in Dutch, is an insurance policy for entrepreneurs It covers any damage caused by you, your employees, or your products to other people and their property whilst carrying out work.
Do I need business liability insurance?
Business liability insurance is not mandatory but it is a sensible choice for many business owners. For example, if you run the risk of causing damage to other people or their property whilst carrying out your work. Business liability insurance protects your business against the financial consequences of claims for damages.
Personal liability insurance
Personal liability insurance does not cover damage arising during business activities. This applies even if you have a sole proprietorship (eenmanszaak).
Although business liability insurance is not mandatory, a client or trade association may demand that you have it. Your policy document is proof that you have AVB
Video: On top of business risks
Vinsent Hooimeijer, account manager at Interpolis, explains how to limit your liability as a self-employed professional without staff.
On top of business risks (Bedrijfsrisico’s de baas)
What does business liability insurance cover?
The AVB usually covers:
- damage to things (material damage)
- damage to persons (personal injury)
- financial damage indirectly caused by an accident because someone can no longer work
What is not covered by an AVB?
Business liability insurance does not cover financial loss caused by a professional error or incorrect advice given by you or your staff. For this, you need professional liability .
Real-life examples
Anything can go wrong in your business. In the examples below, business liability insurance covers the damage:
- Karin receives clients in her coaching practice. A loose cord causes a client to fall. The latter breaks his hip and is unable to work fully for weeks. There is personal injury and financial damage.
Consequence: the client holds Karin liable. Karin must compensate the client's medical expenses and loss of income.
- James is a carpenter and drops his drill on a client's wooden floor. Part of the floor has to be replaced. In this case, there is material damage.
Consequence: the customer holds Abdul liable and he has to pay for the repair.
- Abdul imports hair dye under his own brand, but the composition of the dye is flawed. Customers suffer an allergic reaction. There is personal injury.
Consequence: customers hold James liable. James has to pay his customers' medical expenses.
What does business liability insurance cost
The cost of business liability insurance varies. Some business owners pay around €10 a month, whilst others pay more than €100 a month. How high your premium is depends on:
- your profession.
- the turnover of your business.
- whether and how many staff you employ.
In general, the higher your business risks, the higher your premium. A higher turnover or having many employees can also mean a higher premium.
Premium is deductible
The premium you pay for business insurance is deductible when you file your income tax or profit tax return. Include the premium cost in the calculation of your hourly rate as well.
Why are SBI codes important for insurance?
SBI stands for Standard Business Classification. Your SBI code is the code for the business activity under which you are registered in the Business Register. It is important that your SBI code matches the work you carry out as an entrepreneur.
Insurers use your SBI code, amongst other things, to calculate your premium. If you carry out work that does not correspond to the activities you have declared, this may affect your insurance cover.
Example of activities and insurance
You have registered an online shop with KVK, but you also sometimes install kitchens. You have not registered this as a business activity with KVK. When installing a kitchen, you cause damage. Because this activity was not included when you took out the AVB, your insurer can decide not to cover this damage.
Do you often carry out different activities?
Report this to KVK via My KVK and to your insurer. KVK will then also register your other activities. The insurer can adjust your premium accordingly. This way, you can be sure that damage is covered for all your activities.